

Super.com-Cash Advance, Travel
by Super (previously SnapTravel)
4.5
- Safety
- 100% Safe
- Category
- Finance
- Ratings
- 4.5
- Price
- Free
- Download
- 1.00M
This app is secure, reliable, free to install, and offers fast downloads without any risks or malware.
Screenshots
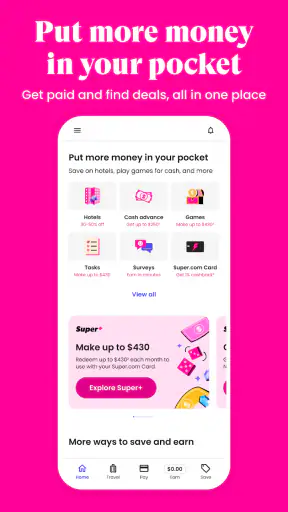
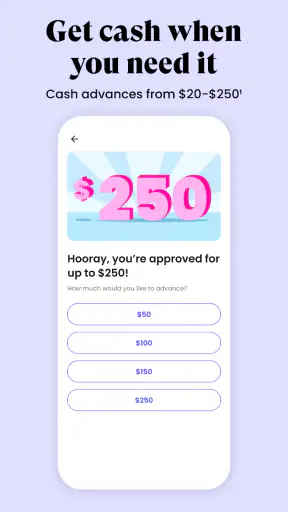
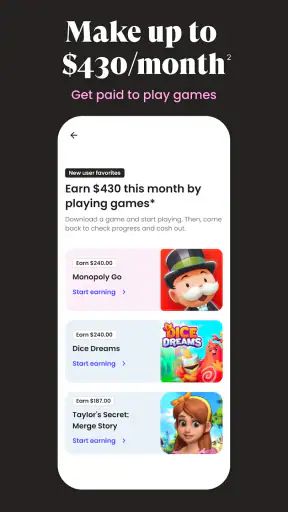
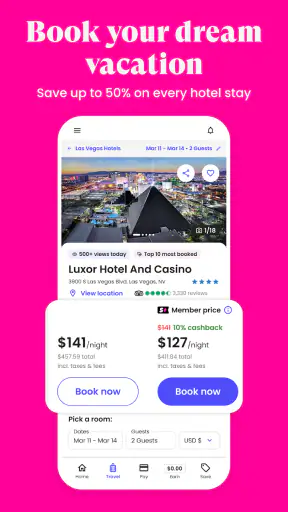
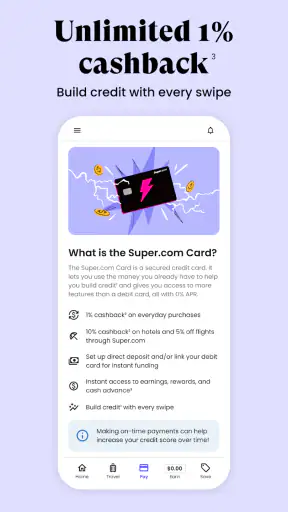
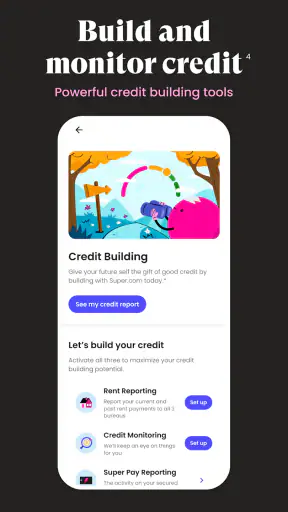
 Analysis by Getfullapps
I tested Super.com-Cash Advance, Travel as the kind of finance app that tries to put several money tasks in one place. It comes from Super, previously known as SnapTravel, and its focus is broader than a standard budgeting tool: saving, earning, travel planning, and access to money are presented together. That combination can be useful in a household where one person is watching daily spending while another is arranging a trip, but it also means you need to understand where personal financial information begins and shared-device convenience ends.
My first impression was that this is not an app I would treat like a casual travel browser. It belongs to the finance category, and the decisions made inside it can affect real spending. I would recommend approaching it as a personal financial workspace rather than a family noticeboard. The app is free to install, has an Everyone content rating, and runs on devices using at least iOS or Android version 10. Its current version is 14.10.8, so keeping the app updated is a sensible part of using it responsibly.
How Super.com works in an everyday shared household
Imagine a couple preparing for a weekend away. One person wants to compare travel options and look for ways to reduce the cost, while the other is trying to keep enough money available for rent, groceries, and upcoming bills. A single app that combines travel-related activity with money features may feel convenient because both people can discuss the same general goal without jumping between several services.
That convenience has a boundary, though. I would not assume that a shared phone or tablet should become a shared financial account. If the device belongs to the household, each person still needs to know which account is signed in and whether the information on screen belongs to them. A travel search may be harmless to discuss together, but cash-advance activity, earnings, balances, and personal details deserve a more private approach.
In my view, the best shared-use pattern is cooperative but not blended. One person can use the app to research a trip, then bring the options into a household conversation. The other person can independently check the budget before anyone commits to spending. This avoids the common mistake of treating a convenient all-in-one app as if it were a joint bank account or a family finance dashboard.
The practical rule is simple: share decisions, not automatically every account screen. That distinction matters more here than it would with a basic weather or recipe app. Super.com deals with money-related choices, so a household should agree on who uses the account, who reviews transactions or offers, and who makes the final decision before borrowing or spending.
What I found useful for travel planning
The travel side is most appealing when you are already thinking about the cost of a trip rather than merely searching for somewhere to go. Instead of viewing travel as an isolated booking task, I found it more natural to use the app as part of a wider money check: what can we afford, what needs to be saved, and would a particular option put pressure on the rest of the month?
Articles to Explore Next

Uber Eats Makes Dinner Easier to Manage, but the Fees Add Up

Google Photos Turns a Camera Roll Into a Library You Can Find Your Way Through

Canva on Mobile: Adopt It for Quick Visuals, Test It for Demanding Work

Google Drive Keeps Work Moving Until It Doesn’t

Switching to Weather - By Xiaomi Means Relearning Your Forecast Routine

Ludo King and the Social Life of a Lucky Six
That broader context is the main reason I would choose it over a conventional travel-only app. A typical booking service is usually better when your only goal is to find dates, destinations, or accommodation quickly. Super.com makes more sense when travel is connected to your wider financial planning. The trade-off is that an all-in-one design may require more attention from the user, because you are moving between different financial purposes rather than completing one narrowly defined task.
For a household, I would use it before booking rather than during a rushed checkout. Sit down together, decide the maximum amount you are comfortable spending, and use the app to explore the available route or travel opportunity. Then pause before using any borrowing-related option. That pause is important because a short-term solution can make a trip possible today while creating a less comfortable repayment period later.
Setting up clear boundaries from the beginning
When I install a finance app on a shared device, I start with account boundaries instead of features. I check whose email address or phone number is connected, which person will receive account messages, and whether the device is protected by a screen lock. These are ordinary precautions, but they prevent confusion later when two people assume they are looking at the same information or believe someone else is monitoring the account.
Super.com is free to download, but “free” should not be interpreted as “without financial consequences.” The app may bring together services that involve saving, earning, travel, or access to money, and each action needs to be judged on its own terms. I would read the conditions shown for any financial product carefully, especially repayment details, eligibility language, and any costs displayed before proceeding. If those terms are unclear, I would stop and get clarification rather than treating the app like a normal shopping tool.
I also recommend separating exploration from commitment. A person can browse travel possibilities or learn how a feature works without immediately applying for or accepting anything. In a shared household, this is especially useful because one person may be researching on behalf of everyone else. Research should not accidentally become authorization.
Another helpful habit is to decide in advance which notifications are private. A message about a trip may be fine to appear on a shared screen, while a financial alert may reveal sensitive information. I would review the device’s notification behavior and avoid leaving the app open when another person could easily access it. The app itself cannot replace a household agreement about privacy.
Coordinating money decisions without mixing identities
Super.com can support a conversation, but I would not rely on it to coordinate a household unless every person understands exactly what the app is showing. For example, one partner might research travel while the other tracks the household budget in a separate system. That is not a weakness unique to this app; it is a reminder that an all-in-one finance service does not automatically become a shared budgeting system.
My preferred workflow is to give each task a clear owner. The person planning the trip can collect the relevant travel information. The person responsible for the household budget can compare the expected cost with upcoming obligations. Both can then agree on whether the plan is sensible. If a cash advance is being considered, the person whose finances are involved should make that decision personally, after reviewing the repayment impact.
This approach also helps when a teenager or younger family member uses the same device. They may be allowed to look at travel ideas, but that does not mean they should handle a financial application or make a money decision for an adult. The Everyone rating describes the app’s content age classification; it should not be read as a recommendation that every age group independently use every financial function.
I would also avoid saving passwords or leaving an active session available simply because the device stays at home. Household trust is not the same as unlimited account access. A partner, roommate, or child may be trusted in daily life while still not being the right person to view personal financial information. Clear boundaries protect everyone from accidental changes as well as deliberate misuse.
Age, trust, and the right level of supervision
Because the app carries an Everyone content rating, it is easy to assume that age is not a meaningful consideration. In finance, it is. A young person may understand how to navigate the interface but still lack the experience to evaluate borrowing, repayment, or the long-term effect of a financial decision. I would treat the age label as a statement about content suitability, not as a substitute for adult guidance.
For an adult using a personal phone, I see Super.com as a potentially convenient way to bring several money-related activities together. For a shared family tablet, I would be more cautious. I would let children participate in a general conversation about travel costs or saving goals, but keep account access and financial decisions with the responsible adult. Nothing about an accessible interface removes that responsibility.
Trust also matters between adults. If one person installs the app and the other later finds an unfamiliar financial screen, the problem may be confusion rather than wrongdoing. Agreeing on the app’s role beforehand avoids that situation. Is it being used for one person’s account, for travel research, or as part of a broader household plan? The answer should be explicit.
Compared with a traditional bank app, Super.com feels more varied because it combines financial and travel-oriented purposes. A bank app is usually the clearer choice for checking established accounts, moving money within familiar banking services, or maintaining a strict record of household finances. Compared with a travel marketplace, Super.com may be more relevant when affordability and money management are central to the decision. I would not expect it to replace either tool completely.
Where the app can create friction
The biggest limitation is the breadth of its promise. Saving, earning, travel, and access to money are very different needs. Putting them together can save app switching, but it can also make the experience feel less focused than a dedicated service. If you only want to book travel, a specialized travel app may get you to the relevant information faster. If you only want detailed spending analysis, a dedicated budgeting tool or your bank’s own application may offer a clearer routine.
I would also be careful with the phrase “cash advance.” Anyone considering that route should think about repayment before thinking about convenience. An advance may solve a short-term gap, but it is not the same as increasing income or reducing expenses. I would use the feature only after checking the complete terms presented in the app and confirming that repayment fits comfortably into the next budgeting period.
Another point is that the app’s usefulness depends on your willingness to manage several purposes thoughtfully. Someone who wants a single, highly specialized tool may find the combined approach distracting. I personally prefer the flexibility when I am planning travel alongside broader money decisions, but I would not use that flexibility as a reason to open financial products casually.
The app has attracted a substantial user base, with more than a million installs and an average rating of 4.5 from roughly thirty-one thousand ratings. Those figures suggest that many people find the concept worthwhile, but they do not tell me whether it fits a particular household. A positive rating cannot decide whether a borrowing option is appropriate for your circumstances, and it cannot replace reading the terms shown for your account.
Three smarter ways I would use it
First, I would use a “research, review, decide” sequence for travel. Research in the app, review the total effect on the household budget elsewhere if necessary, and decide only after both people involved agree. This prevents the excitement of finding a convenient travel option from turning into an unplanned financial commitment.
Second, I would use separate conversations for travel and borrowing. They may appear next to each other in an all-in-one app, but they are not the same decision. A trip can be postponed, shortened, or redesigned; borrowing introduces a repayment obligation. Keeping those discussions separate makes the risk easier to see.
Third, I would make a shared-device checklist part of the routine: confirm the signed-in person, review visible notifications, close the session after use, and never assume that a family member’s access is automatically appropriate. These steps are not flashy features, but they are more valuable than convenience when an app handles personal financial information.
A fourth useful habit is to use the app as a comparison point rather than the only source of truth. If a travel option looks attractive, compare the overall cost with a normal travel service. If a financial option looks helpful, compare its repayment impact with simply waiting, reducing the trip, or using an existing emergency fund. Super.com can be part of the decision without being the entire decision.
Who should choose it, and who should skip it?
I think Super.com is a good fit for an adult who likes the idea of combining travel discovery with several money-related tools and is comfortable reviewing terms carefully. It may also suit a couple that wants to coordinate a trip while keeping personal account responsibility clear. The free entry point makes it easy to explore, but the real value depends on disciplined use rather than simply installing it.
I would skip it if you want a straightforward banking replacement, a detailed shared household ledger, or a travel-only search experience with no additional financial context. I would also avoid using it as a quick answer to recurring money shortages. If you regularly need advances to cover ordinary expenses, a conversation with a qualified financial adviser or a careful review of your budget may be more useful than another short-term solution.
For a child or young teenager, I would not hand over independent control of the financial side merely because the app is rated for Everyone. Super.com can be discussed in an educational setting, but responsible adults should retain control of accounts and decisions. On a shared device, the safest arrangement is one where the adult user signs in deliberately and closes the app when finished.
My household verdict
After looking at Super.com through a shared-household lens, I see a useful but somewhat demanding finance app. Its strongest idea is bringing travel and money decisions closer together, which can help when you are trying to plan a trip without ignoring everyday expenses. Its weakest point is the temptation to treat that convenience as permission to combine accounts, blur responsibilities, or use borrowing without a repayment plan.
Super, previously SnapTravel, has built an app that is more ambitious than a conventional travel service. The current version is 14.10.8, and its long availability since June 27, 2019, helps explain why it has become familiar to a large audience. I would still judge it by the specific feature and terms in front of me, not by its age, install count, or rating.
My recommendation is cautious but positive: try Super.com-Cash Advance, Travel if you want one place to explore travel and money options, and use it with clear personal boundaries. Keep shared planning separate from private account access, treat cash advances as serious financial decisions, and compare the app with dedicated alternatives before committing. Used that way, it can be a practical addition to a household’s planning routine. Used casually on a shared device, it can create more confusion than convenience.
For me, the deciding question is not whether the app can do several things. It is whether those things match the way your household already makes decisions. If you value an integrated view and are willing to slow down before accepting a financial option, it is worth exploring. If you need a simple bank account manager, a transparent family budget, or a focused travel browser, another specialized app will probably serve you better.
Pros
- Combines cash advances, travel deals, and financial tools in one app.
- Travel booking options can help users compare flights, hotels, and car rentals.
- Cash advance requests are handled digitally without visiting a physical branch.
- Membership perks may provide extra savings on selected travel and lifestyle services.
- Clear repayment schedules help users understand when an advance is due.
Cons
- Cash advance eligibility and limits vary by user and are not guaranteed.
- Membership fees may reduce the value if you rarely use the included benefits.
- Travel prices and availability can change before a booking is completed.
- Some financial features may be limited by location, income, or account verification.
- Late repayment or other charges may make advances more expensive than expected.
FAQs for Super.com-Cash Advance, Travel
What is Super.com-Cash Advance, Travel?
Super.com is a financial and travel app that combines short-term cash advance services with travel-related tools and offers. Depending on your location and eligibility, the app may help you access funds before payday, compare or book travel, and manage selected financial services from one account. Available features, limits, fees, and travel benefits can vary by country and by the information provided during registration.
How does the cash advance feature work?
The cash advance feature is designed to give eligible users access to part of their expected income before their regular payday. After creating an account and completing the required verification, the app may display the amount available and the applicable delivery options. Approval is not guaranteed, and users should carefully review repayment dates, subscription costs, transfer fees, and all terms before accepting an advance.
Does Super.com charge fees or require a subscription?
Super.com may offer different plans, memberships, or transaction options, and some services can involve subscription charges, expedited transfer fees, or other costs. The exact pricing depends on the product selected, your location, and your account status. Before confirming a cash advance or travel purchase, review the final payment screen and cancellation terms so you understand recurring charges and the total amount payable.
Can I use Super.com to book flights, hotels, or other travel services?
The travel section may provide access to travel search, booking, discounts, or membership-based benefits, depending on the market where you use the app. Prices, availability, cancellation rules, baggage conditions, and refund policies are determined by the relevant travel provider. It is important to verify every booking detail before payment, especially dates, passenger names, airport information, and restrictions attached to promotional rates.
Is Super.com safe, and what information is needed to use it?
Super.com may request personal, contact, financial, identity, and employment-related information to provide financial services and comply with verification requirements. Users should download the app only from an official store, protect their login details, and read the privacy policy before registering. Financial products can involve real costs and repayment obligations, so never share account credentials and contact official support if activity appears unfamiliar.

Super.com-Cash Advance, Travel
This site provides independent information about third-party apps and is not affiliated with, or the owner, developer, or distributor of, any app featured here. App names, logos, and trademarks belong to their respective owners. Developer details are provided for reference; please contact the developer directly via service@super.com, visit https://www.super.com, or review their https://www.super.com/legal#super-2.










